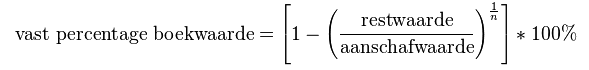Add an asset group

You use asset groups to classify assets. An asset group contains settings such as the general ledger accounts for journalising, which apply to all of the linked assets. Generally, asset groups are coupled to balance sheet items such as inventory, machines, computers, etc. You can link a periodic allocation table to each asset group to take account of any seasonal influences on the depreciation.

The fields you complete for an asset group are preferred values for new assets with the exception of Dev. period distribution. When you add an asset, Profit copies these values, but you can set them differently for each asset.

Note:

You can no longer change the ledger accounts for writing off of an asset group if the assets of the asset group have been journalised. If you still want to change the settings of an asset group after you have journalised, you first have to roll back the journal entries.

You can import asset groups by selecting Financial / Management / Import activa en contract / Fixed assets groups.

To add an asset group:

  1. Go to: Financial / Fixed assets / Asset group.
  2. Click on: New.
  3. Enter the description.
  4. Enter a value in Rounding depreciation.

    The rounding method applies to all periods.

  5. Specify whether Profit should round the depreciations and select the administration and the journal (variable general journal) in which Profit should post the journal entries.
  6. Click on: Next.
  7. You can now register data concerning the commercial and/or fiscal depreciation method.
  8. Select a value for Depreciation method.

    Click here for more information.

    Profit supports the following depreciation methods:

    • Straight line depreciation percentage

      Each year, you depreciate a fixed percentage of the difference between the purchase costs and the residual value.

      Formula: Depreciation per year = (purchase value + additional costs - residual value) / presumed period of use

      Example: 

      You purchase a machine with the following features: Purchase price of € 14,000, term of 5 years and a residual value of € 2,000.

      Depreciable: 14,000.- - 2,000.- = 12,000.-

      Depreciation per year: 12,000.- / 5 = 2,400.-

      Depreciation per month: 2,400.- / 12 = 200.--

      If you have only used an asset for part of the year then you may only depreciate over that part. Suppose you bought the machine on 1 October of this financial year. For this financial year you may then depreciate: 3 * 200 = 600

    • Straight line depreciation amount

      You record a fixed annual amount for the depreciations. In the last financial year, you write off any differences with regard to the total depreciable amount.

    • Direct depreciation

      You depreciate the asset completely in the first year. The asset is actually registered in fixed assets, possibly with a specified residual value. Journalising of the complete depreciation is done in the first year.

    • Random depreciation

      You can decide the annual depreciation yourself (only permitted for fiscal depreciation). As a consequence, you can influence the company result. Normally, this is only used for a company just starting up.

    • Degressive method (Belgium)

      With this method, you depreciate at twice the linear percentage in the first years. Starting from the year that the depreciable amount is lower than the normal linear amount, you continue to depreciate linearly. For this method, Profit takes into account that the annuity with degressive depreciation does not amount to more than 40% of the purchase value. In Belgium the depreciation amount may be a maximum of 40% of the purchase value.

    • Percentage of the book value asset sale

      Each year you depreciate a fixed percentage of the book value asset sale. You depreciate until the residual value or the bottom value of the asset has been reached. If you create for the asset and you choose this depreciation method then you must enter the Depreciation period and Depreciation percentage. Profit automatically calculates the residual value after the depreciation period and the percentage have been entered.

      Formula:

      Fin_Afschrijvingsmethoden vaste activa (40)

      Where n is the number of years within which you want to depreciate

      Example:  

      You purchase a machine with the following features: Purchase price of € 10,000, depreciation period of 5 years and a residual value of € 1,000.

      The depreciation percentage is 25% per year (12 periods)

      Depreciation first year: 10,000 euros * 0.25 = 2.500 euros

      Depreciation second year: (10,000 euros - 2,500 euros) * 0.25 = 1,875 euros, and so on until the 5th year.

      In the 5th year, the remainder (- residual value) is also depreciated, divided over the 12 months.

      If you use the Percentage of the book value asset sale depreciation method, you can clear the depreciation period and then enter the depreciation percentage and the residual value. This calculates the number of years for the depreciation period and again adjusts the residual value, because Profit uses entire years for depreciation period calculations.

      If the asset is retained after this depreciation period, you can enter a lower residual value and enter a new depreciation regimen for the same asset.

  9. Select a value for Asset type.
  10. Enter a value in Depreciation period.

    This value, multiplied by the number of periods in the fixed assets period table, results in the number of periods over which an asset is depreciated.

    If you select the Straight line depreciation percentage method, Profit automatically determines the Depreciation percentage based on the formula 100 / Depreciation period.

  11. If required, enter a value for Dev. period distribution.

    In principle, Profit calculates the same depreciation amount for each period. You can also take account of seasonal factors. In this case, link a periodic allocation table to the asset group.

    Example:

    You have an agricultural business and only use specific harvesting and other machines in the autumn. You add a periodic allocation table with the following layout:

  • January - July: 4% per month
  • August and September: 30% per month
  • October - December: 4% per month

    You link this periodic allocation table to the asset group ‘Harvesting machines’. Profit uses these percentages when calculating the depreciation of the assets linked to this asset group.

  1. Click on: Next.
  2. Select the correct ledger accounts in Depreciations and Sales.
  3. Click on: Finish.

Directly to

  1. Configure fixed assets
  2. Authorisation
  3. Authorisation per administration
  4. Fixed assets period table
  5. Add a journal
  6. Add ledger accounts
  7. Fixed assets settings
  8. Add an asset group
  9. Block a fixed assets financial year